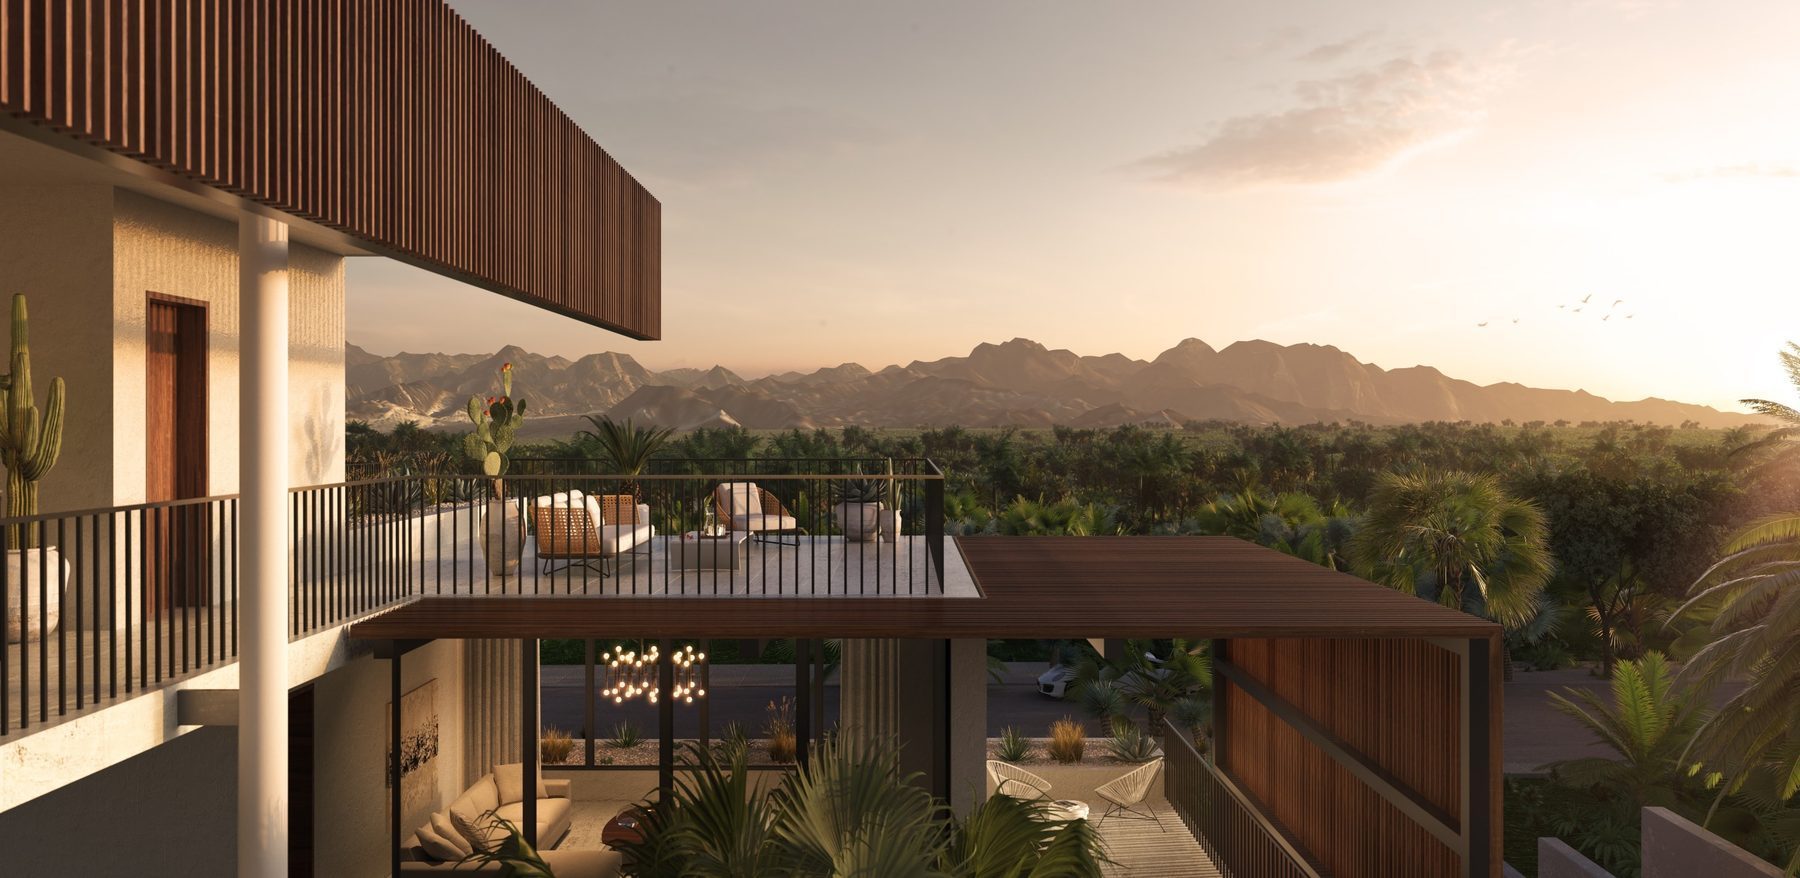
Here is something I have learned coaching hundreds of professionals through real estate decisions: the sandwich generation — people simultaneously supporting children and aging parents — represent the largest group of buyers who want Cabo property and talk themselves out of it. Not because the math does not work, but because they never run the math. They assume it is irresponsible. They assume the timing is wrong. They assume they need to wait until the kids are settled and the parents are stable. What they do not assume is that it might be the smartest financial and emotional decision they make this decade.
Key Takeaways
- ✓ Well-located Cabo condos start at $250K–$400K at Fonatur, Cabo Bello, and Club Campestre — less than most US resort markets
- ✓ Rental income of $15K–$30K/year can offset 60–100% of carrying costs, making the property self-funding
- ✓ A US HELOC or cash-out refinance keeps monthly payments at $1,500–$2,500 without depleting retirement accounts
- ✓ Cabo as a multigenerational gathering point has measurable psychological and family cohesion benefits
- ✓ Accessible ground-floor units near H+ Hospital serve the needs of aging parents visiting from the US
Juggling Family and a Cabo Dream?
We specialize in helping buyers navigate competing financial obligations while finding the right Cabo property.
Contact UsWho You Are (And Why You Think You Cannot Do This)
I know your profile because I coach people like you for a living. You are 45 to 60. Your household income is $150,000–$400,000. You own a home with $200,000–$600,000 in equity. Your retirement accounts are solid — $500K to $2M — but they feel untouchable because the financial advisor says do not withdraw early. You have at least one child still requiring financial support (college tuition, first apartment, wedding, or simply still on the family phone plan). And you have at least one parent who needs regular help — whether that is financial, logistical, or emotional.
Your financial obligations feel like they are pulling in every direction. And the idea of adding a second home to the equation seems reckless. Here is what I want to challenge: that assumption is based on the cost model of US resort real estate, not Mexican resort real estate. And those are two very different conversations.
The Numbers That Change Everything
Let me give you three scenarios that represent the typical sandwich generation buyer. All three assume you are financing through a US HELOC at 8% interest, renting the property when you are not using it, and you personally use the property 4–6 weeks per year.
Scenario 1: The $300K Fonatur Condo
A two-bedroom, two-bathroom condo in Fonatur, San Jose del Cabo. Walkable to the Art District, restaurants, and groceries. Nothing fancy — but clean, modern, and in a location that tourists love.
- Purchase price: $300,000
- HELOC monthly payment (interest-only at 8%): $2,000
- Annual carrying costs (HOA, tax, insurance, trust, utilities, management): $12,000
- Net rental income (renting 9–10 months, managed): $18,000–$24,000
- Your net annual cost after rental offset: $0–$6,000
- Monthly out-of-pocket (including HELOC): $2,000–$2,500
For $2,000–$2,500 per month — less than a car payment on a luxury SUV — you own a property in Mexico that your family uses a month and a half per year, generates enough income to cover its own carrying costs, and appreciates at 3–5% annually. When you sell the SUV analogy to your spouse, it lands.
Scenario 2: The $450K Cabo Bello Condo
A two-bedroom unit at Cabo Bello on the Corridor, with a swimmable beach — one of the few on the entire Corridor. Better location, better amenities, slightly higher price.
- HELOC monthly payment: $3,000
- Annual carrying costs: $16,000
- Net rental income: $22,000–$30,000
- Your net annual cost after rental offset: $0–$4,000
- Monthly out-of-pocket: $3,000–$3,350
Scenario 3: The $500K Club Campestre Villa
A three-bedroom at Club Campestre with Jack Nicklaus golf, pool, and enough space for three generations to visit comfortably. This is the multigenerational play.
- HELOC monthly payment: $3,333
- Annual carrying costs: $18,000
- Net rental income: $25,000–$35,000
- Your net annual cost after rental offset: $0–$3,000
- Monthly out-of-pocket: $3,333–$3,583
The pattern across all three scenarios: rental income covers carrying costs, and your monthly outlay is the financing payment — which builds equity in a property that appreciates.
The Multigenerational Value Nobody Puts on a Spreadsheet
Let me tell you what happens when a sandwich generation family buys a Cabo property. I have watched it play out dozens of times.
The first trip is just the couple. They unpack, they exhale, they remember why they wanted this. The second trip includes the kids — college age, maybe bringing a girlfriend or boyfriend. Suddenly the family has a shared destination that is not anyone's childhood home with all its baggage. The third trip includes the parents. Grandma sits on the balcony, watches the ocean, and says something she has never said: "I understand why you love this place."
What you have created is a multigenerational gathering point that works precisely because it is neutral territory. It is not your parents' house where you revert to being 14. It is not your house where your parents feel like guests. It is the family's place — a shared asset that gives everyone a reason to come together.
I cannot put a dollar value on that. I can tell you that the families I work with who made this purchase rank it as one of the best decisions they have ever made, specifically because of what it did for family dynamics during the most stressful years of the sandwich generation experience.
Accessibility for Aging Parents
If your parents are in their 70s or 80s, accessibility is not optional — it is a dealbreaker filter. Here is what to look for:
- Ground-floor or elevator-served units: Stairs eliminate half the condo inventory for mobile-limited parents. Focus on developments with elevators (most newer Corridor developments have them) or ground-floor units
- Walk-in showers: Step-over tubs are a fall risk. Many newer condos have walk-in showers; older units can be retrofitted for $2,000–$5,000
- Flat entry: No steps from the parking area or lobby to the front door. This eliminates some hillside properties and older developments with exterior stairways
- Proximity to medical facilities: Properties within 15 minutes of H+ Hospital on the Corridor give you peace of mind for elderly visitors. San Jose del Cabo, Fonatur, and the central Corridor all qualify
- Climate control: Functioning AC is non-negotiable for elderly visitors during warm months. Verify that the unit has modern mini-split systems, not window units
The communities I recommend for sandwich generation buyers with accessibility needs: Fonatur (walkable, flat terrain, close to services), Cabo Bello (ground-floor Corridor options), and Club Campestre (some single-level villa configurations). All three are within a 15-minute drive of H+ Hospital.
Financing Strategies That Preserve Your Safety Net
The cardinal rule for sandwich generation buyers: do not touch retirement accounts. Your 401(k) and IRA are not piggy banks — they are your future, and raiding them for a second home while you still have dependents is objectively risky. Instead:
HELOC on Your Primary Residence
If your US home has $200,000+ in equity (and most sandwich generation buyers have significantly more), a HELOC provides flexible financing at 7–9% with interest-only payments during the draw period. You borrow what you need, pay interest only for 5–10 years, and pay down principal when your cash flow frees up (after college tuition ends, for example).
Cash-Out Refinance
If rates are favorable, refinancing your primary residence and pulling out $200K–$400K gives you purchase capital at a fixed rate. Monthly payment increases on your primary mortgage by $1,000–$2,000 depending on how much you pull — offset by the rental income from the Cabo property.
Family Partnership
Here is one that works beautifully for the sandwich generation: pool resources with siblings. Three siblings contribute $100K–$150K each to buy a $400K property. Formalize the arrangement through a co-ownership agreement or Mexican corporation. Split usage weeks, split costs, and give the whole extended family a shared gathering point. I have seen this work exceptionally well when the property is positioned as "the family's place" rather than any one sibling's investment.
Ready to Explore Value Communities in Los Cabos?
We help sandwich generation buyers find properties that work financially without compromising on quality of life.
Book a Strategy CallThe Timing Argument: Why "Later" Is More Expensive
The biggest trap for sandwich generation buyers is the belief that the right time to buy is after the obligations lighten. After the kids graduate. After mom is settled. After the 401(k) hits a magic number. The problem with "after" is that it keeps moving — and meanwhile, two things happen:
- Property prices increase. Cabo real estate has appreciated 4–8% annually over the past decade. The $300K condo you are looking at today was $220K five years ago and will be $400K five years from now. Every year you wait costs you $12,000–$24,000 in appreciation you do not capture
- Your parents age. The window during which your parents can comfortably travel to Cabo, navigate the airport, enjoy the beach, and create memories with their grandchildren is finite. It is measured in years, not decades. A property you buy when your parents are 72 gives you 10–15 years of family trips. A property you buy when they are 82 gives you 2–5. The math is not just financial
I have had buyers tell me, tears in their eyes, that they wish they had bought five years earlier — not because the property was cheaper then (though it was), but because their parents could still enjoy it. That is a cost no spreadsheet captures and no financial advisor factors in.
The Sandwich Generation Buying Playbook
- Run the actual numbers. Do not guess. Sit down with the scenarios above, plug in your real equity, your real income, and your real expenses. The gap between "I cannot afford this" and "this actually works" is often smaller than you think
- Focus on value communities. Skip Palmilla and Querencia for now. Fonatur, Cabo Bello, and Club Campestre deliver 80% of the lifestyle at 40% of the cost. You can always trade up when the sandwich obligations lift
- Plan for rental income from day one. This is not a vacation home that might someday become a rental. Structure it as a rental property that your family uses a few weeks a year. The mindset shift matters for the financing decision, the property selection, and the management approach
- Get the accessibility right. If your parents will visit, ground floor or elevator access is non-negotiable. Filter for this early — it eliminates properties quickly and saves you from falling in love with something your mom cannot use
- Involve the family. If siblings can contribute, the per-person cost drops dramatically. If adult children can manage the rental (marketing, guest communication) as a side income project, you save 20–25% in management fees. This works best when everyone has skin in the game
The Permission You Did Not Know You Needed
Here is what I tell every sandwich generation buyer who sits across from me looking guilty about even considering this: you are not being irresponsible. You are being strategic. A Cabo property that covers its own costs through rental income, appreciates at market rates, and gives your family a gathering point during the most intense years of your life is not a luxury. It is an investment in the three things that matter most — your financial future, your family's connection, and your own mental health.
You have spent the last 15 years putting everyone else first. Your kids' tuition, your parents' needs, your employer's demands. Buying a property in Cabo is not abandoning those obligations — it is adding an asset that serves all of them while also serving you.
The timing is not perfect. It never will be. But the window for creating multigenerational memories with the people you love most is closing a little bit every year. Run the numbers. If they work — and for most sandwich generation earners they do — stop waiting for permission that nobody else is going to give you.
Your Family Deserves a Gathering Place
We help sandwich generation families find Cabo properties that work financially and bring three generations together. Let us run the numbers for you.
Contact Us TodayFrequently Asked Questions
Can I really afford a Cabo property while supporting kids and parents?+
The short answer is: probably, if you approach it strategically. The key insight is that Cabo has a wider price range than most buyers realize. A well-located two-bedroom condo at Fonatur or Cabo Bello starts at $250,000–$400,000 — significantly less than a comparable property in most US resort markets. Financing through a US HELOC or cash-out refinance on your primary residence can keep monthly payments at $1,500–$2,500. If you rent the property during months you are not using it, net rental income of $15,000–$25,000/year can offset 60–100% of carrying costs. The property pays for itself while giving your family a gathering place.
What Cabo communities offer the best value for sandwich generation buyers?+
Three communities stand out for value: (1) Fonatur in San Jose del Cabo — walkable to restaurants, galleries, and services, two-bedroom condos from $250K–$450K, lower HOA fees than Corridor properties. (2) Club Campestre — Jack Nicklaus golf community with condos starting around $300K–$500K, strong value relative to the amenity package. (3) Cabo Bello — on the Corridor with a swimmable beach, condos from $300K–$500K, significantly below Palmilla or Chileno Bay pricing but with legitimate Corridor location and beach access. All three offer the quality of life without the premium pricing.
How do I finance a Cabo property when my cash flow is stretched?+
The most common financing strategies for sandwich generation buyers: (1) HELOC on US primary residence — tap existing equity at rates of 7–9%, interest-only payments during the draw period. (2) Cash-out refinance — pull $200K–$400K from a paid-down primary residence. (3) Self-directed IRA or Solo 401(k) — for business owners, these vehicles can hold foreign real estate (with restrictions). (4) Family partnership — pool resources with siblings to buy a shared property (use a Mexican corporation or carefully structured fideicomiso). (5) Seller financing — some Cabo developers and resale sellers offer 12–36 month payment plans at reasonable rates.
Are there accessibility-friendly Cabo communities for aging parents?+
Yes, and this should be a key filter for sandwich generation buyers. Ground-floor condos with flat entry, walk-in showers, and elevator access are available at: Fonatur (many buildings are 2–3 stories with ground-floor units), Copala at Quivira (newer construction with modern accessibility features), and Club Campestre (single-level villa options). The Corridor hotels often have ADA-style rooms in their residential components. H+ Hospital is centrally located on the Corridor for medical access. Ask your agent specifically about step-free entry, bathroom accessibility, and proximity to medical facilities.
Should sandwich generation buyers rent their Cabo property?+
Almost always yes. Rental income is what makes the math work when you are juggling competing financial obligations. The strategy: block out your personal use weeks (2–8 weeks/year for most sandwich generation buyers), rent the rest through a professional property manager. Net income of $15,000–$30,000/year on a $350K–$500K condo turns a stretch purchase into a self-funding asset. The property becomes less of a 'luxury splurge' and more of a 'diversified investment that my family happens to use a few weeks a year.' That reframing matters when you are making the case to your spouse or your financial advisor.
How does healthcare access in Cabo work for visiting elderly parents?+
Los Cabos has strong private healthcare infrastructure that works well for visiting elderly family members. H+ Hospital and BlueNet Hospital both have 24/7 emergency services, English-speaking staff, and specialists in geriatric-relevant fields (cardiology, orthopedics, internal medicine). Private consultation fees of $30–$60 mean a doctor visit does not require insurance navigation. For parents with chronic conditions, bring medications from the US (90-day supply is allowed), have medical records accessible electronically, and know the location of the nearest private hospital from your property. Medical evacuation insurance ($300–$500/year) covers emergency transport to the US if needed.
Aaron Cuha
Real Estate Advisor & Los Cabos Market Expert
Real estate advisor and founder of Living In Cabo. 15+ years helping families navigate complex real estate decisions. Strategic partner with Ronival — Baja's largest brokerage.